
Investing in real estate is one of the most popular ways to build long-term wealth and earn a regular income. Whether you are planning to purchase a residential flat, an independent house, a commercial shop, or an office space, understanding rental yield is essential before making an investment decision.
Rental yield helps investors estimate how much rental income a property can generate compared with its purchase price. It also allows you to compare different properties and identify opportunities that may offer better returns.
For investors exploring opportunities in Nagpur and other growing Indian cities, calculating rental yield can help make property investment decisions more informed and financially practical.
1. What Is Rental Yield in Real Estate?
Rental yield is the annual rental income generated by a property, expressed as a percentage of its purchase price or total investment cost.
For example, if you purchase a flat for ₹50 lakh and receive ₹20,000 per month in rent, your annual rental income will be ₹2.4 lakh. Your rental yield will be 4.8% when calculated against the purchase price.
Rental yield is commonly divided into two types:
- Gross rental yield: The annual rental income divided by the property's purchase price, expressed as a percentage.
- Net rental yield: The annual rental income after deducting relevant property expenses, divided by the total investment cost, expressed as a percentage.
Gross yield provides a quick comparison, while net yield gives a more realistic picture of the income you may retain.
2. Understand the Gross Rental Yield Formula
The gross rental yield formula is simple:
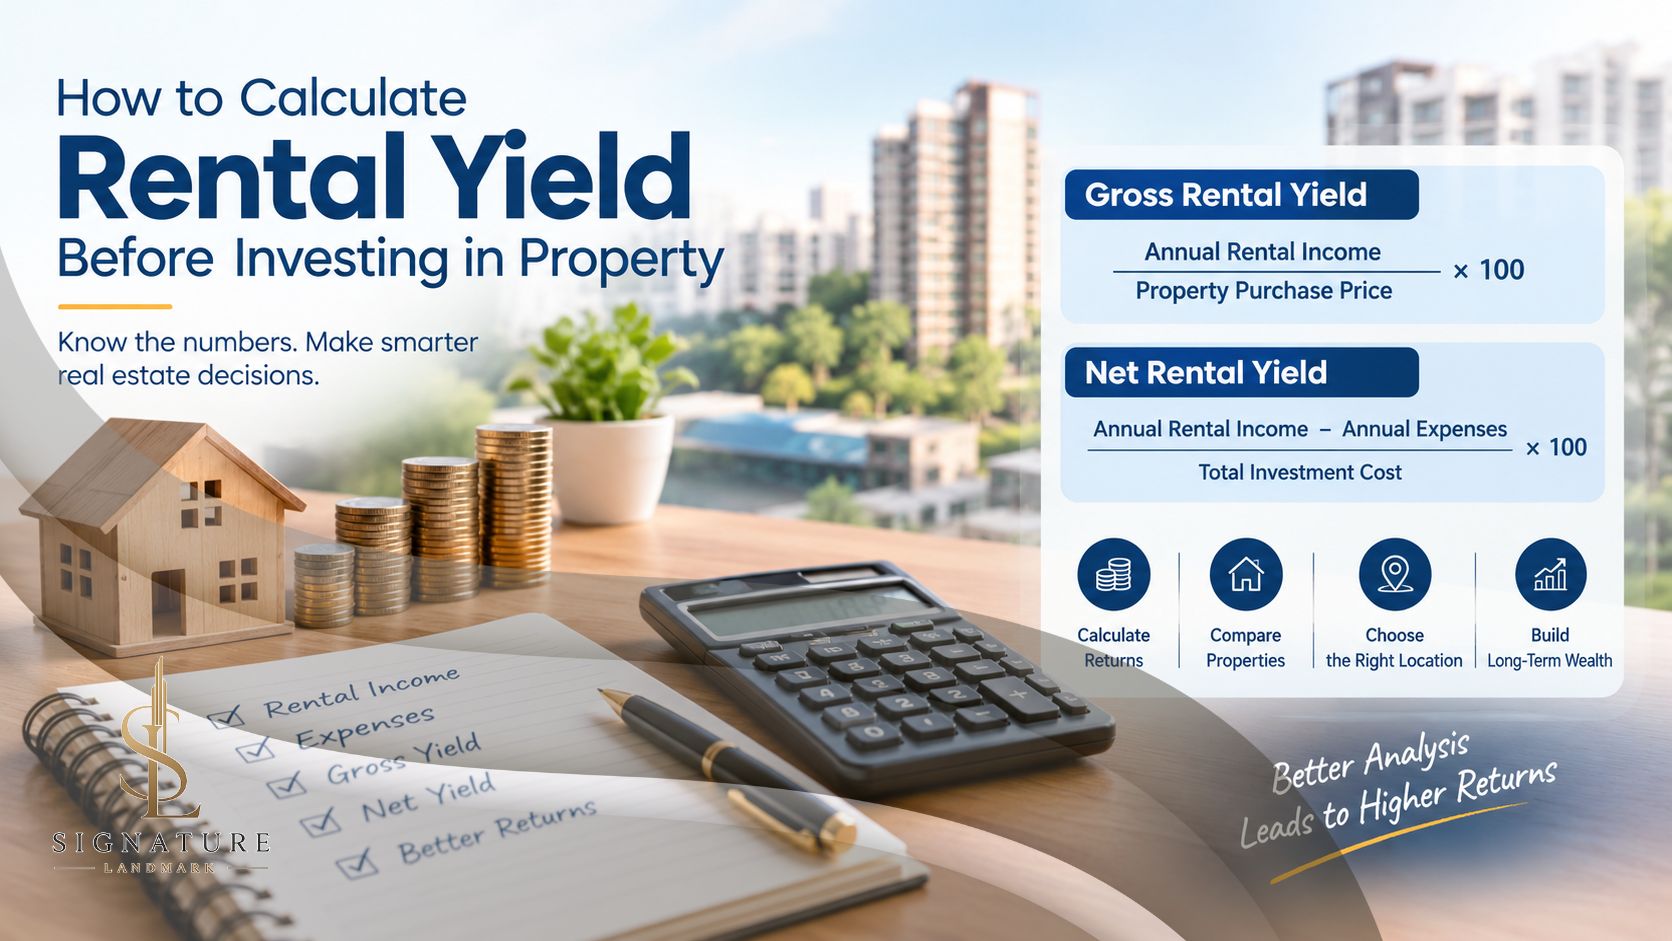
Gross Rental Yield = (Annual Rental Income ÷ Property Purchase Price) × 100
To calculate annual rental income, multiply the monthly rent by 12.
For example, suppose you purchase a residential property in Nagpur for ₹40 lakh and rent it out for ₹16,000 per month.
- Property purchase price: ₹4,000,000
- Monthly rental income: ₹16,000
- Annual rental income: ₹192,000
Calculation:
Gross Rental Yield = (₹1,92,000 ÷ ₹40,00,000) × 100
Gross Rental Yield = 4.8% per year
This means the property generates gross rental income equal to 4.8% of its purchase price annually, before expenses.
3. Calculate Net Rental Yield for Accurate Returns
Gross rental yield does not include expenses such as maintenance, property taxes, repairs, insurance, or periods when the property remains vacant.
To estimate your actual rental returns, calculate net rental yield.
Net Rental Yield = (Annual Rental Income − Annual Property Expenses) ÷ Total Investment Cost × 100
Consider a property purchased for ₹40 lakh, generating ₹1.92 lakh in annual rent.
Assume the estimated annual expenses are:
| Expense | Annual cost |
|---|---|
| Property maintenance | ₹18,000 |
| Property tax | ₹8,000 |
| Repairs and other costs | ₹6,000 |
| Total expenses | ₹32,000 |
Your annual rental income after these expenses is ₹160,000.
Net Rental Yield = (₹1,60,000 ÷ ₹40,00,000) × 100
Net Rental Yield = 4% per year
This calculation provides a better estimate of the property's income performance. For greater accuracy, include registration charges, stamp duty, brokerage, furnishing costs, and other acquisition expenses in your total investment cost. Also account for expected vacancy periods and any applicable management fees.
4. Consider All Costs Before Buying a Property
The purchase price is not the only expense involved in real estate investment. Additional costs can significantly affect your returns.
Before purchasing a property, consider:
- Stamp duty and registration: Government charges payable during the purchase.
- Brokerage fees: Payments made to property agents, where applicable.
- Maintenance charges: Regular expenses for building upkeep and common facilities.
- Property taxes: Applicable municipal taxes.
- Repairs and renovations: Costs required to make the property suitable for tenants.
- Vacancy periods: Time when the property does not generate rental income.
- Loan expenses: Interest and other financing costs, if you purchase using a home loan.
For a property bought primarily to earn rental income, calculating returns on the full acquisition cost rather than just the advertised price gives a more useful comparison.
5. Compare Residential and Commercial Property Rental Yields
Different property types can produce different rental returns depending on location, tenant demand, purchase price, and operating costs.
Residential properties, such as flats and houses, may attract families, working professionals, and students. They can offer steady rental demand in well-connected residential areas.
Commercial properties, such as shops and offices, may generate higher rental income in some locations. However, they can also involve longer vacancy periods, higher maintenance costs, or greater dependence on local business activity.
When comparing residential and commercial investments, evaluate the net yield alongside tenant quality, lease terms, vacancy risk, and resale potential. Do not assume that commercial properties always provide higher returns.
6. Why Location Matters for Rental Yield
Location plays a major role in determining both property prices and rental demand.
In Nagpur, investors may research areas with access to employment hubs, educational institutions, hospitals, public transport, and major roads. Locations connected to business and industrial developments, including MIHAN and nearby employment centers, may be worth evaluating for suitable rental opportunities.
However, infrastructure development does not guarantee higher rents or property appreciation. Actual results depend on project completion, local supply, tenant demand, and the price at which you purchase.
Before investing, compare similar properties in the same locality. Research current asking rents, recently achieved rents where available, vacancy levels, and the total cost of ownership.
7. Common Rental Yield Calculation Mistakes to Avoid
Investors sometimes make mistakes that cause them to overestimate rental returns.
Using expected rent instead of realistic rent: Research comparable properties and consider how long it may take to find a tenant.
Ignoring vacancy periods: A property that remains empty for one or two months will earn less than 12 months of rent.
Forgetting recurring expenses: Maintenance, repairs, taxes, and management fees reduce the income you retain.
Focusing only on gross yield: A property with a higher gross yield may have higher expenses and a lower net yield.
Ignoring financing costs: If you borrow money, compare rental income with loan repayments and interest costs. Rental yield alone does not measure cash flow or the overall return on your equity.
8. Is Rental Yield Enough to Make an Investment Decision?
Rental yield is an important metric, but it should not be the only factor influencing your decision.
Real estate investors should also evaluate potential capital appreciation, property condition, legal documentation, tenant demand, resale liquidity, and the risks associated with the location.
For example, one property may offer a higher rental yield but limited resale demand, while another may offer a lower yield in a location with stronger long-term prospects. Neither outcome is guaranteed, so investors should assess both income and risk.
Also remember that rental income may be subject to applicable income tax rules. Your final after-tax return can therefore differ from your net rental yield.
Conclusion
Calculating rental yield before investing in property helps you understand the income potential of a real estate asset. Start with gross rental yield for a quick comparison, then calculate net rental yield after accounting for expenses, vacancy, and the full investment cost.
For buyers considering residential flats, plots with rental potential, commercial shops, or office spaces in Nagpur, careful research can help identify properties that fit their financial goals.
At Signature Landmark, we believe informed property decisions begin with understanding the numbers, evaluating the location, and checking the property's legal and financial details. Before making a purchase, compare multiple investment options and assess both rental income and long-term risks.
Smart property investment begins with the right calculations, realistic expectations, and thorough research.