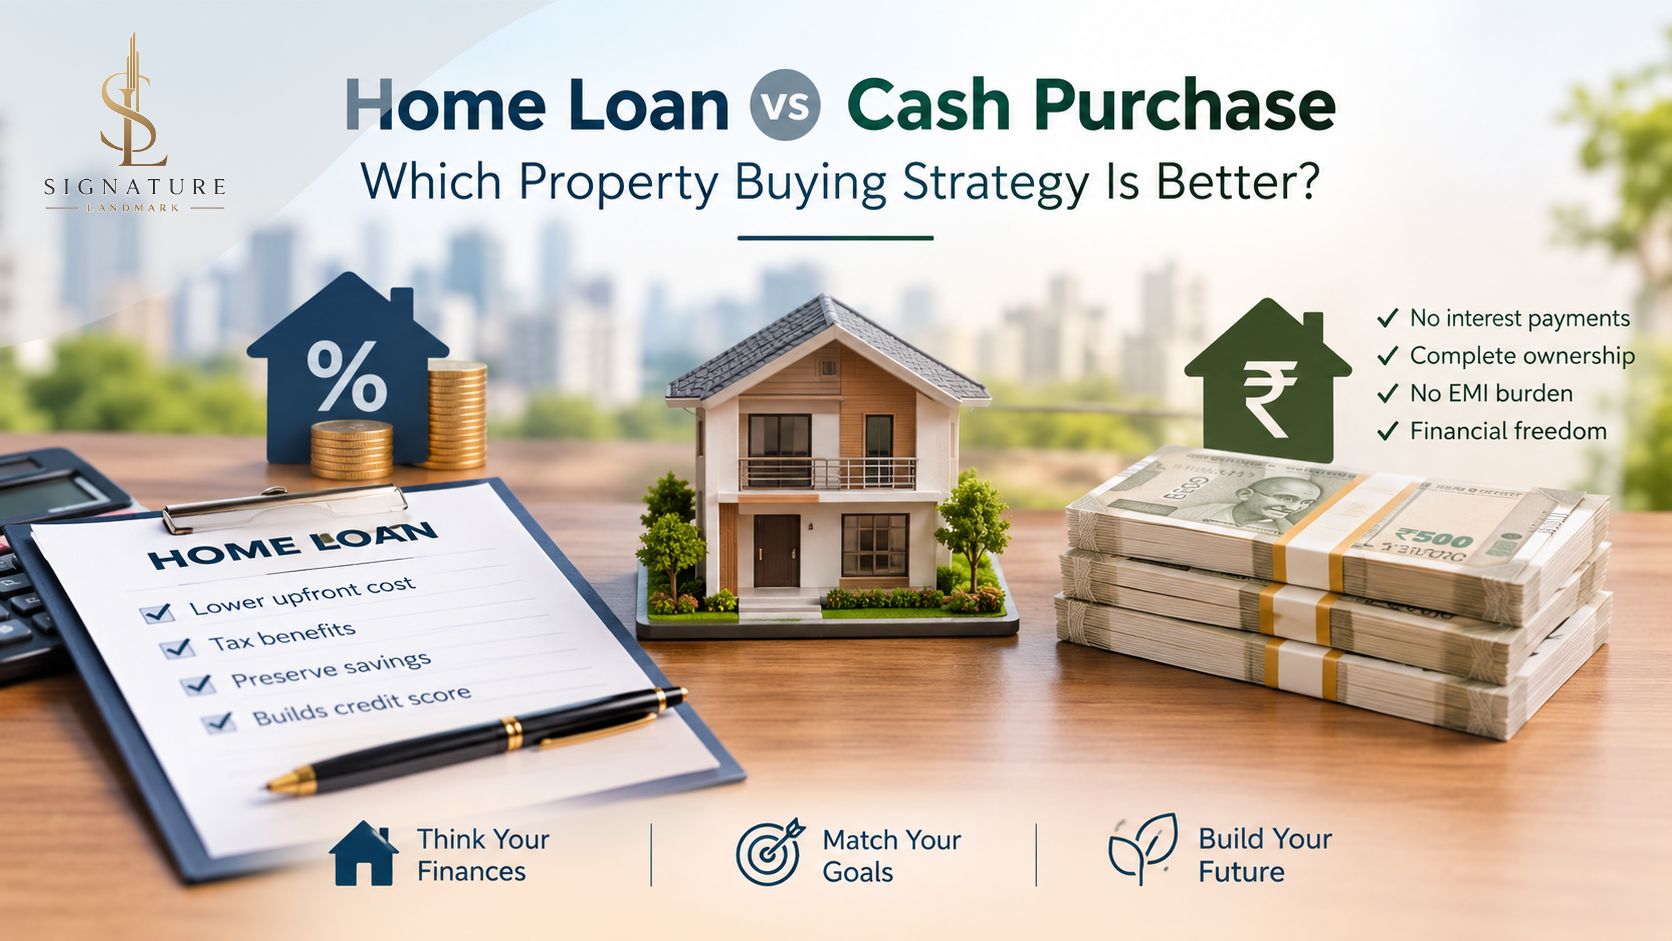

Buying a property is one of the biggest financial decisions in life. Whether you are purchasing your first home, investing in residential property, or buying commercial real estate, choosing the right payment strategy is important. One of the most common questions property buyers face is whether to purchase a property through a home loan or pay the entire amount in cash.
Both options have advantages and disadvantages. A home loan allows buyers to purchase property without using all their savings, while a cash purchase provides complete ownership without monthly EMI obligations. The right choice depends on your financial condition, investment goals, income stability, and plans.
In this blog, let's understand the differences between home loans and cash purchases and identify which strategy is better for property buyers in India.
1. Understanding Home Loan and Cash Purchase
Before choosing a property buying strategy, it is important to understand both options.
Home Loan: A home loan is a financial facility offered by banks and housing finance companies to help individuals purchase residential property. The buyer pays a certain percentage of the property value as a down payment, while the remaining amount is financed by the lender. The borrower repays the loan through monthly EMIs over an agreed period, usually ranging from 10 to 30 years.
Cash Purchase: A cash purchase means buying a property using your available funds without taking a home loan. The buyer pays the entire property amount using savings, investments, or other available financial resources. This eliminates loan interest and monthly EMI obligations.
2. Advantages of Buying Property Through a Home Loan
Home loans are popular among Indian property buyers because they make property ownership more accessible.
A. Preserve Your Savings
One of the biggest advantages of a home loan is that you do not need to spend all your savings on purchasing a property. You can make a down payment and keep the remaining money available for emergencies, business requirements, or other investments.
B. Tax Benefits
Eligible home loan borrowers can claim tax benefits under applicable provisions of the Income Tax Act, subject to property usage, tax regime, and other conditions.
For eligible self-occupied properties, interest deductions may be available under Section 24(b), and principal repayment may qualify under Section 80C under the old tax regime, subject to prescribed limits.
C. Build a Credit Score
Regular and timely EMI payments can help build a positive credit history. A good credit profile may improve your eligibility for future loans and other financial products.
D. Opportunity to Invest Elsewhere
Instead of investing your entire savings in one property, you can retain some funds for other investment opportunities, such as mutual funds, business expansion, or other assets.
However, these investments carry market risks and may not necessarily generate returns higher than your home loan interest rate.
3. Disadvantages of Buying Property Through a Home Loan
Although home loans offer financial flexibility, they also involve certain costs.
- Interest Payments: You repay more than the original property price because of interest charged over the loan tenure.
- Monthly EMI Burden: Regular EMIs can affect your monthly budget and lifestyle.
- Loan Approval Process: Banks evaluate your income, credit score, employment, and financial documents before approving a loan.
- Additional Charges: Processing fees, legal charges, insurance costs, and other expenses may increase the overall borrowing cost.
- Financial Risk: Job loss, business difficulties, or unexpected expenses can make EMI payments challenging.
Therefore, buyers should carefully calculate their repayment capacity before taking a home loan.
4. Advantages of Buying Property Through Cash
A cash purchase can be an attractive option for buyers who have sufficient financial resources.
A. No Interest Payments
The biggest benefit is that you do not have to pay interest to a bank or financial institution. This can result in significant savings, especially compared with long-term loans.
B. Complete Financial Ownership
Once the purchase is legally completed and registered, you own the property without any home loan liability or lender mortgage.
C. No Monthly EMI Pressure
Without monthly loan repayments, you have greater flexibility in managing your income and expenses.
D. Strong Negotiating Position
Buyers who can make immediate payment may sometimes negotiate better prices or favorable payment terms with sellers. However, discounts are not guaranteed.
E. Peace of Mind
A debt-free property can provide financial security and peace of mind, particularly for buyers planning long-term residential use.
5. Disadvantages of Cash Property Purchase
Despite its advantages, paying the entire property amount upfront may not always be the smartest financial decision.
- Reduced Liquidity: A large portion of your savings becomes locked in real estate.
- Emergency Fund Risk: You may have limited funds available for medical emergencies, business needs, or unexpected expenses.
- Opportunity Cost: Money invested in property cannot simultaneously be used for other investment opportunities.
- Portfolio Concentration: Investing most of your wealth in one property increases exposure to a single asset and location.
- Additional Expenses: Stamp duty, registration charges, maintenance, property taxes, and other expenses still apply.
Cash buyers should ensure that they have sufficient funds remaining after purchasing the property.
6. Home Loan vs Cash Purchase: Key Differences
| Factors | Home Loan | Cash Purchase |
|---|---|---|
| Initial payment | Down payment | Full property value |
| Interest | Applicable | No loan interest |
| Monthly EMI | Required | Not required |
| Savings | Partially preserved | Significantly utilized |
| Tax benefits | May be available | No home loan deductions |
| Financial flexibility | Depends on EMI | No EMI burden |
| Ownership | Subject to the lender's mortgage rights | No lender mortgage |
| Documentation | Loan and property documents | Property documents |
7. Which Strategy Is Better for Property Investment?
The answer depends on your investment objectives.
Choose a Home Loan If:
- You have a stable income and sufficient EMI repayment capacity.
- You want to preserve your savings.
- You have other investment opportunities.
- You are purchasing a property for long-term appreciation or rental income.
- You want to maintain financial liquidity.
Choose Cash Purchase If:
- You have sufficient funds after maintaining an emergency reserve.
- You want to avoid long-term debt.
- You prefer financial independence.
- You do not have attractive alternative investment opportunities.
- You want to avoid interest expenses and EMI obligations.
For property investors, taking a home loan can sometimes improve investment flexibility. However, rental income and property appreciation should be evaluated carefully against interest costs, maintenance, taxes, and vacancy risks.
8. Important Factors to Consider Before Making a Decision
Before finalizing your property purchase, consider these important factors:
- Financial Stability: Evaluate your income, existing liabilities, and monthly expenses.
- Emergency Fund: Maintain sufficient savings for unexpected financial situations.
- Interest Rates: Compare home loan interest rates from different banks.
- Property Location: Research connectivity, infrastructure, employment opportunities, and future development.
- Investment Horizon: Decide whether you are buying for personal use, rental income, or long-term appreciation.
- Legal Verification: Check the property's title, approved building plans, RERA registration where applicable, and other necessary documents.
A well-researched property purchase can help reduce financial risks and support long-term wealth creation.
Conclusion
Both home loans and cash purchases can be effective property buying strategies. A home loan provides financial flexibility, preserves liquidity, and makes property ownership accessible without using all your savings. On the other hand, a cash purchase eliminates interest payments, reduces financial liabilities, and offers freedom from monthly EMIs.
There is no single strategy that works for every buyer. The best decision depends on your financial position, investment goals, risk tolerance, and future requirements.
Before purchasing any residential or commercial property, carefully evaluate your options and make an informed decision.
At Signature Landmark, we believe that every property investment should begin with the right information and proper planning. Whether you are buying your dream home or investing in real estate, choosing the right property is the first step towards a secure financial future.